Can Defence Become HBL Engineering’s Next Growth Driver?
India’s defence manufacturing boom is creating a large opportunity. But for HBL Engineering, the more useful question is much narrower: how much defence revenue can the company actually add before Kavach begins to slow?
HBL entered FY26 with ₹1,946.13 crore of sales and finished FY26 at ₹3,252 crore, with Kavach contributing almost 50% of sales. Management expects Kavach to remain important through FY28 but has said that both sales and PBT could decline from FY29 as competition increases.
That creates a measurable gap.
If Kavach revenue were to fall 20%, the reduction would be roughly ₹325 crore based on its FY26 contribution. A 30% decline would create a gap of roughly ₹488 crore. Defence therefore does not need to become another ₹1,500-crore business immediately to become strategically important. It needs to generate enough incremental revenue to replace a meaningful part of that potential gap.
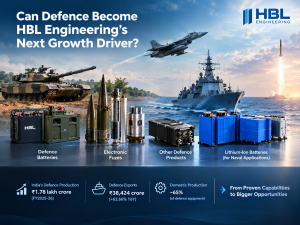
The starting point is already visible. HBL reported ₹211.58 crore of Defence & Aviation Batteries revenue in FY26, down from ₹227.22 crore in FY25. This is an established business covering batteries for aircraft, missiles, armoured vehicles, torpedoes and submarines, with exports also contributing.
The potential second leg is electronic fuzes. HBL says it has developed fuzes for grenades, artillery shells, rockets, missiles and air-dropped bombs, while its FY26 annual report says grenade-fuze sales have already started and Army and 155mm artillery approvals are expected during 2027.
The third is lithium-ion defence batteries. HBL has invested about ₹200 crore in R&D and a dedicated production plant for defence cells, with management saying the investment should be profitable from the first year.
The question is therefore no longer whether HBL has a defence business.
It is whether these three businesses can collectively become large enough to replace the revenue that a maturing Kavach cycle could eventually take away.
Defence Is Already An Established HBL Business
HBL’s defence exposure is almost as old as the company itself.
The company says its first products were aircraft batteries, eventually making HBL a leading supplier of batteries to the Indian Air Force. Its current defence battery portfolio covers aircraft, missiles, armoured vehicles, torpedo propulsion and submarine propulsion. HBL also says exports are a significant contributor to this business.
The important number is ₹211.58 crore.
That was HBL’s FY26 revenue from Defence & Aviation Batteries, down from ₹227.22 crore in FY25. This is the portion of the defence franchise that investors can already see in reported financials.
The newer opportunities are less transparent.
HBL does not separately disclose electronic-fuze revenue in its financial statements because fuzes sit within the broader electronics business alongside railway and other electronics products. It also does not separately disclose revenue from defence lithium-ion batteries.
That distinction matters.
The defence investment case therefore has three different layers:
- Established revenue: ₹211.58 crore from Defence & Aviation Batteries in FY26.
- Commercialising opportunity: electronic fuzes, where initial sales have begun and additional approvals are pending.
- Future optionality: lithium-ion defence batteries and other specialised defence products whose eventual revenue contribution has not yet been separately disclosed.
This prevents a common analytical mistake: treating every product under development as if it were already contributing to HBL’s earnings.
For now, only the ₹211.58 crore battery business provides a clean audited defence revenue base.
Electronic Fuzes Could Be The Biggest Defence Opportunity
Electronic fuzes are arguably the most important new piece of HBL’s defence strategy because this business has already progressed beyond pure development.
HBL began developing electronic-fuze technology in 2006. The company says it has developed the required components and subsystems in-house, with no proprietary imported items, and has developed fuzes for grenades, artillery shells, rockets, missiles and air-dropped bombs. A licensed manufacturing facility has been established in Telangana.
The qualification process is significant because these products cannot simply be manufactured and sold immediately. HBL explains that fuzes have to be tested on actual weapons and warheads at declared ranges, with the availability of weapons and testing facilities affecting the approval timeline.
That makes the latest developments important.
HBL’s FY26 annual report says its electronic fuzes for grenades have received Ministry of Home Affairs approval and sales have started. The company expects Indian Army approval during 2027 and also expects approval for fuzes used in artillery shells fired from 155mm guns during 2027. Several other types remain in the approval pipeline.
The product pipeline is broader than those two applications. HBL’s earlier disclosures identified electronic-fuze applications across grenades, artillery, rockets, missiles and air-dropped bombs. Its strategy is therefore not dependent on a single ammunition programme.
But investors should be careful with the revenue opportunity.
HBL has not separately disclosed FY26 fuze revenue, annual fuze production capacity, average selling prices or a specific FY28 fuze revenue target.
That means the correct analytical conclusion is not that fuzes will generate a particular amount by FY28.
The evidence is that the business is moving from development towards commercialisation, with the next major milestones being Army and 155mm approvals and subsequent production scale-up.
The FY26 annual report also identifies electronic fuzes among the four business units expected to contribute most to sales over the next four years.
That makes fuzes a genuine growth candidate but the revenue has to be demonstrated through actual production and orders.
Why Fuzes Could Scale Faster Than HBL’s Existing Defence Business?
The attraction of electronic fuzes is not simply that ammunition demand is large.
It is the combination of qualification, indigenous technology and potential production volumes.
HBL says it has spent years developing the technology internally. Once a fuze has completed customer-specific testing and approval, the company has a qualified product rather than simply a prototype. That creates a different competitive position from selling a generic industrial component.
The opportunity also spans several ammunition categories.
A single approved fuze can serve a specific application, but HBL’s broader development programme covers multiple applications. That creates the possibility of building a portfolio rather than depending on one defence platform.
However, there is an important economic distinction between products.
Management has previously explained that high-volume ammunition fuzes can have lower margins per unit, while specialised products can command better economics. It has also highlighted the difference between developing a product in small quantities and reliably manufacturing it at scale.
That means the next stage of the fuze story should be judged on volume as well as qualification.
A successful approval without meaningful production would not transform HBL’s financial profile.
The critical progression is:
approval → order → production → repeat order → capacity utilisation.
That is also why the absence of separately disclosed fuze revenue is currently important. Investors cannot yet determine how much of HBL’s electronics revenue comes from fuzes.
The first clear evidence will come when HBL begins reporting material fuze orders or provides product-level revenue and capacity information. Check our latest video for more details.
Lithium-Ion Defence Batteries: ₹200 Crore Invested, But Revenue Is Still Unproven
The second major defence opportunity is lithium-ion technology.
HBL has deliberately avoided trying to become a mass-market lithium-ion cell producer. Management has said the company chose a specialised defence niche instead, where customers require high-performance products in relatively small volumes and where domestic manufacturing carries strategic importance. The Indian Navy is the primary focus.
The financial commitment is already substantial.
HBL’s FY26 annual report says it has invested about ₹200 crore in R&D and a modern production plant for defence lithium-ion cells. The technology was licensed from the Naval Science and Technological Laboratory, and the company says there is no foreign collaboration involved. It also says the plant is adequate for foreseeable demand and that capacity can be increased through line balancing if required.
Management had earlier said that cumulative investment in this area would be ₹200 crore or less by the end of FY26 and that it expected the business to be profitable from the first year.
That creates an interesting capital-efficiency question.
HBL has told investors how much it is investing, but not yet how much annual revenue that investment can support.
The company has not separately disclosed the plant’s annual cell capacity in GWh, expected utilisation, average realisations, a FY28 revenue target or a product-level ROCE target.
Therefore, ₹200 crore of investment should not be converted into an assumed ₹X crore of annual revenue.
The correct interpretation is that HBL has created manufacturing capacity for a specialised defence market. The financial opportunity becomes clearer only when Navy-related orders translate into actual production.
This is particularly important because HBL’s existing defence battery business already has a long history with submarines and torpedoes. The lithium-ion initiative is therefore an extension into higher-energy-density technology rather than a completely new customer relationship. HBL also identifies the Indian Navy among its long-term government customers.
The next proof point is simple: orders and utilisation of the new plant.
The Most Important Number: How Much Defence Revenue Is Needed After Kavach?
This is where the defence thesis becomes measurable.
HBL’s FY26 revenue was ₹3,252 crore, and Kavach represented roughly half of the company’s sales. That implies a Kavach revenue base of approximately ₹1,626 crore.
Management’s earlier disclosures indicate that Kavach should remain strong through FY28, although its contribution can eventually decline as the railway network becomes increasingly covered and competition develops. The FY26 annual report continues to identify Kavach as one of the company’s four largest business units expected to contribute over the next four years.
That creates a useful replacement-revenue calculation:
| Potential Kavach decline | Approx. revenue gap |
| 10% | ₹163 Cr |
| 20% | ₹325 Cr |
| 30% | ₹488 Cr |
These are scenario calculations, not forecasts. They simply show how much annual revenue would disappear if Kavach’s FY26 contribution declined by those percentages.
Now compare those figures with HBL’s existing defence battery business.
FY26 Defence & Aviation Batteries revenue was ₹211.58 crore.
Therefore:
- A 10% Kavach decline would create a revenue gap smaller than HBL’s existing annual defence battery revenue.
- A 20% decline would create a ₹325 crore gap, about ₹113 crore more than the entire FY26 defence battery business.
- A 30% decline would create a ₹488 crore gap, about ₹276 crore above FY26 defence battery revenue.
This changes the question investors should ask.
Defence does not need to become a ₹1,000-crore business immediately to become
strategically important to HBL.
If the existing battery business remains around its current scale, then fuzes and new defence battery applications together need to add roughly ₹113-276 crore to cover a 20-30% Kavach revenue gap.
That is a much more realistic hurdle for the defence thesis.
It also shows why merely pointing to India’s ₹1.78 lakh crore defence-production figure is not enough. HBL’s opportunity is ultimately determined by whether its own products can generate incremental revenue at this scale.
Defence Does Not Have To Replace Kavach Alone
The Kavach comparison should not be interpreted as saying defence is the only business capable of replacing a future railway slowdown.
HBL itself is building a broader portfolio.
Its FY26 annual report identifies four business units expected to contribute most to sales over the next four years: Kavach, industrial nickel-cadmium batteries, electronic fuzes and electric drive trains for trucks. The company also says industrial electronics and special defence products currently in development are expected to be commercialised by FY30.
That makes the defence opportunity more interesting because it does not need to carry the entire post-Kavach transition.
Instead, HBL is effectively building several replacement engines.
The distinction is important for investors.
- Ni-Cd batteries are an established business.
- Electronic fuzes are moving from qualification into commercialisation.
- Electric drive trains are an emerging industrial-electronics opportunity.
- Special defence products and underwater electronics remain further out on the development curve.
This portfolio approach is consistent with HBL’s historical business model. The company says it deliberately enters engineering-intensive niches, develops technology internally and grows products incrementally rather than relying on one mass-market product.
Defence therefore does not have to become HBL’s single replacement for Kavach.
It needs to become one of several businesses capable of absorbing the eventual decline in Kavach’s contribution.
India’s Defence Boom Provides The Backdrop, Not The Earnings Forecast
The broader industry numbers are supportive.
India’s defence production reached ₹1.78 lakh crore in FY2025-26, while exports reached ₹38,424 crore. The private sector’s contribution to production increased to approximately ₹42,000 crore, or 24% of the total.
For HBL, the more relevant part of this trend is the growing emphasis on indigenous technology.
The company describes its strategy as identifying technology gaps in India, developing engineering-intensive products and manufacturing them domestically. That approach is visible across its defence portfolio: aircraft and naval batteries, electronic fuzes and newer underwater-electronics applications.
The company also has long-standing relationships with the Indian Air Force, Indian Navy and Ministry of Defence laboratories.
That gives HBL an established position inside the defence ecosystem.
But the industry numbers should remain the backdrop rather than the valuation argument.
India can produce more defence equipment without every HBL product automatically gaining market share.
For HBL, the relevant evidence will come from product approvals, orders, production volumes, revenue and returns on capital.
What Could Make Defence A Material Growth Engine?
There are now three numbers to keep in mind.
First, HBL already generates ₹211.58 crore from Defence & Aviation Batteries.
Second, a 20-30% decline in the implied FY26 Kavach revenue contribution would create a potential ₹325-488 crore annual revenue gap.
Third, HBL has two major opportunities- electronic fuzes and lithium-ion defence batteries, that could increase the defence contribution, but their individual revenues are not yet separately disclosed.
That creates a clear earnings bridge.
If the existing defence battery business remains at roughly ₹200 crore, fuzes and newer defence applications would need to add another ₹113-276 crore to offset a 20-30% Kavach decline.
That is the number worth watching.
The fuze business has the clearer near-term commercial path because grenade-fuze sales have already started and further Army and 155mm approvals are expected in 2027.
Lithium-ion batteries have a larger disclosed capital commitment but less disclosed revenue visibility.
This makes the two opportunities different.
Fuzes are primarily a qualification-and-scale story.
Lithium-ion is primarily a commercialisation-and-capacity-utilisation story.
The existing defence battery business, meanwhile, provides the recurring base.
If all three develop successfully, defence could become a meaningful contributor to HBL’s growth without needing to replace the entire Kavach business by itself.
What Investors Should Watch Next?
The defence thesis can now be tracked through a relatively small set of measurable developments.
- Defence battery revenue
The starting point is ₹211.58 crore in FY26. Investors should watch whether this established business returns to sustained growth, particularly through submarine, torpedo, aircraft and missile applications.
- Electronic-fuze approvals
The next major milestones are Indian Army approval and approval for 155mm artillery-shell fuzes, both expected by HBL during 2027.
- Fuze order conversion
Approval is not the end of the story. The key question is how quickly approvals become production orders and repeat volumes.
- Fuze capacity utilisation
HBL has established a licensed fuze manufacturing facility in Telangana. Actual utilisation and production volumes will show whether the business is scaling beyond qualification batches.
- Lithium-ion revenue
The company has invested about ₹200 crore in defence lithium-ion R&D and manufacturing. Actual Navy orders and production will determine whether that capital starts generating meaningful revenue.
- Return on the lithium-ion investment
Management has said the business should be profitable from the first year. Investors will eventually be able to test that claim through revenue, operating profit and capital employed once commercial production scales.
- Defence’s ability to fill the Kavach gap
This is the most important portfolio-level metric. A 20% decline in the implied FY26 Kavach contribution represents roughly ₹325 crore of revenue; a 30% decline represents roughly ₹488 crore.
If defence revenue begins moving towards that scale while other businesses also grow, the post-Kavach transition becomes considerably more visible.
The Bottom Line
HBL Engineering’s defence story is no longer simply a bet on India’s rising defence spending.
It is an established ₹211.58-crore defence battery business being expanded into electronic fuzes and lithium-ion technology.The electronic-fuze business is the more visible near-term opportunity. HBL has spent years developing the technology, has already started selling grenade fuzes after approval, and expects further Army and 155mm artillery approvals during 2027.
Lithium-ion is the larger capital commitment. HBL has invested about ₹200 crore in R&D and a dedicated plant, with the Indian Navy as a key target market. But revenue capacity, utilisation and product-level returns have not yet been disclosed.
The post-Kavach calculation makes the opportunity easier to understand.
A 20% decline in the implied FY26 Kavach contribution would create a revenue gap of about ₹325 crore. A 30% decline would create a gap of about ₹488 crore.
HBL’s existing defence battery business already contributes ₹211.58 crore. The remaining ₹113-276 crore would have to come from fuzes and other businesses if defence alone were expected to cover such a gap.
That is not an impossible hurdle but it has not yet been demonstrated.
The next phase of HBL’s defence story therefore depends on conversion rather than announcements: fuze approvals into orders, orders into production, lithium-ion investment into Navy revenue, and defence revenue into cash returns.
If those numbers begin appearing in HBL’s financials, defence can move from being a collection of specialised niches to a genuine second growth engine.
Until then, the opportunity is real, but the earnings contribution remains the number investors still need to see.