Can Electronic Warfare Become Data Patterns’ Next Big Growth Engine?
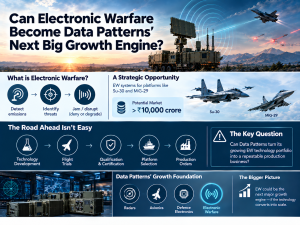
Data Patterns has already built its growth story around radars, avionics and defence electronics. But its next major opportunity could come from a technology that plays a very different role on the battlefield: electronic warfare (EW). Instead of simply detecting or tracking threats, EW systems are designed to identify, disrupt and counter the electronic systems that modern aircraft, missiles and drones depend on.
Data Patterns is developing its own EW portfolio, including the Talon Shield self-protection jammer pod for the Su-30, alongside radar warning receivers, electronic support measures and COMINT/ELINT systems. The broader EW opportunity is estimated at more than ₹10,000 crore, with the jammer component alone estimated at around ₹7,400 crore. But neither number represents Data Patterns' revenue opportunity. The investment question is much narrower: how much of that opportunity can Data Patterns actually capture, and how quickly can it convert development into production?
That matters because Data Patterns generated ₹925 crore of revenue and ₹371 crore of EBITDA in FY26. For EW to genuinely become its “next big growth engine”, it cannot remain a development programme. It needs to become a business capable of adding hundreds of crores of recurring annual revenue.
What Would Actually Qualify As A “Big” EW Growth Engine?
The easiest way to test the claim is to put numbers against it.
Data Patterns' FY26 revenue was ₹925 crore, while EBITDA was ₹371 crore, implying a 40% EBITDA margin.
If EW generated incremental annual revenue of:
- ₹100 crore: total company revenue would reach ₹1,025 crore if everything else stayed unchanged. At a 35-40% EBITDA margin, that EW revenue would represent ₹35-40 crore of EBITDA.
- ₹250 crore: revenue would rise to ₹1,175 crore, with ₹87.5-100 crore of EBITDA at the same margin.
- ₹500 crore: revenue would reach ₹1,425 crore, with ₹175-200 crore of EBITDA at a 35-40% margin.
These are analytical scenarios, not company guidance, and the margin assumption should not be treated as a forecast for EW.
But they establish a useful threshold.
At ₹100 crore, EW would be meaningful but still relatively small, at ₹250 crore, it would become a material contributor, equivalent to more than 27% of FY26 revenue and at ₹500 crore, EW would represent more than half of FY26 revenue.
So the phrase “next big growth engine” should really mean something closer to ₹250-500 crore of annual EW revenue, not simply winning another development contract.
The Existing EW Business Is Important But Its Revenue Is Not Separately Disclosed
There is a critical disclosure gap investors should understand.
Data Patterns already has EW products and programmes, but it does not separately disclose an EW revenue line in the financial information available. Its revenue is reported across broader development, production and product categories rather than giving investors a standalone number for EW.
That means it is impossible to responsibly say that the company currently has, for example, ₹50 crore or ₹100 crore of EW revenue.
What can be established is that EW is already part of the company's product portfolio. Data Patterns has RWR, ESM and COMINT/ELINT systems covering frequencies from 1 MHz to 40 GHz, while its broader EW portfolio includes jamming and electronic countermeasure capabilities. Some of these systems have already been flight-proven on reconnaissance/Netra-class platforms.
This changes how the opportunity should be viewed.
EW is not a completely new business that needs to be built from scratch. But neither can investors yet measure it as a standalone ₹100–500 crore business.
The next evidence has to come from production orders and disclosed revenue contribution.
Talon Shield Is The Critical Near-Term Test
The most important EW programme is the Talon Shield self-protection jammer pod for the Su-30.
The system is being developed as a full suite covering electronics, cooling, mechanical systems and algorithms, with the components being developed in-house. The current stage is progression toward flight trials and qualification, with the research indicating a targeted qualification timeline before December.
This is important because Talon Shield is much further along the value chain than an early-stage concept.
But there are still several unanswered commercial questions.
Data Patterns has not disclosed the final number of aircraft to be equipped, the number of jammer pods it could receive, or a firm production-order value. Therefore, it would be misleading to divide the ₹7,400 crore jammer opportunity by an assumed number of aircraft and call the result Data Patterns' potential revenue.
The better way to look at it is through scenarios.
If the ₹7,400 crore jammer opportunity were treated purely as an addressable pool, then:
- 5% capture = ₹370 crore
- 10% capture = ₹740 crore
- 20% capture = ₹1,480 crore
These are analytical capture scenarios, not management guidance or expected Data Patterns orders.
Even the lowest 5% scenario would be significant relative to FY26 revenue. ₹370 crore would equal roughly 40% of FY26 revenue.
That shows why Talon Shield matters but it also shows why investors should wait for an actual procurement allocation before assigning these numbers to Data Patterns. Check our latest video for more details.
The ₹10,000 Crore EW Market Needs To Be Converted Into A Realistic Opportunity
The headline EW market is estimated at more than ₹10,000 crore, while the jammer component is estimated at roughly ₹7,400 crore.
But Data Patterns cannot realistically address every rupee of that market.
Its actual opportunity depends on the platforms it qualifies for, the products it wins, the procurement route, competition and whether it becomes a selected supplier.
A useful analytical framework is therefore:
₹10,000 crore market → addressable EW programmes → Data Patterns' qualified products → procurement share → production revenue.
If Data Patterns ultimately captured:
| Illustrative capture | Revenue from ₹10,000 Cr market |
| 5% | ₹500 Cr |
| 10% | ₹1,000 Cr |
| 20% | ₹2,000 Cr |
Again, these are scenario calculations, not forecasts.
The 5% case alone would represent more than half of Data Patterns' FY26 revenue. The 10% case would exceed its entire FY26 revenue base.
That is precisely why the opportunity is potentially transformative but also why using the entire ₹10,000 crore as a revenue forecast would be wrong.
More importantly, Data Patterns' opportunity is likely to be built over several programmes rather than one cheque. The portfolio includes fighter EW, RWR/ESM/COMINT/ELINT, counter-drone EW and related threat-emulation systems.
The opportunity becomes much more credible if several of these programmes begin reaching production simultaneously.
Talon Shield Does Not Need To Capture 20% Of The Market To Matter
The capture analysis also puts the Talon Shield opportunity into perspective.
Data Patterns does not need to win 20% of the entire EW market to materially change its financial profile.
A ₹250 crore annual EW business would already equal about 27% of FY26 revenue.
A ₹500 crore annual EW business would equal about 54% of FY26 revenue.
That is the more useful benchmark for investors.
If Talon Shield alone eventually contributes ₹250-500 crore annually, it could qualify as a genuine growth engine. If it contributes only a smaller amount and the rest of the EW portfolio remains in development, then EW would still be an interesting pipeline but not yet a second pillar of the company.
This is why the eventual annual production run-rate matters more than the headline contract value.
A one-time development order does not create a growth engine. A production programme that continues across aircraft, upgrades and follow-on orders can.
Counter-Drone EW Could Reduce Dependence On The Su-30 Programme
The second major piece of the EW thesis is counter-drone warfare.
Here the opportunity is more concrete than simply saying that “drones are growing”.
The proposed counter-drone architecture combines active radar detection, passive ESM/COMINT detection, jamming/countermeasures and tracking systems. The Ministry of Defence has been placing trial orders across multiple vendors, with the requirement described as roughly 10-20 systems from each vendor during the trial phase. Data Patterns already has one or two orders from the Ministry of Defence in this area.
Management expects several hundred crores of contracts from this category during the year, but these were not included in the roughly ₹2,000 crore FY27 order-inflow expectation. The initial orders are expected to be followed by a 2-3 year scaling period if the trials convert into volume procurement.
That makes counter-drone EW potentially important for two reasons.
First, it creates a second route to scale beyond fighter-aircraft EW.
Second, the opportunity is distributed across multiple systems and vendors rather than being dependent on one large platform decision.
But again, the key milestone is conversion from trials into volume orders.
The Counter-Drone Opportunity Could Become A ₹250-500 Crore Business Too
The “several hundred crore” commentary gives investors a useful directional range, although it is not precise enough to treat as guidance.
If counter-drone programmes eventually generate ₹250 crore of annual revenue, that alone would represent roughly 27% of FY26 company revenue.
At ₹500 crore, it would represent more than half.
The important distinction is timing.
The initial 10-20-system trial orders are not equivalent to a ₹250-500 crore recurring business. The latter requires procurement at scale across multiple requirements and successful execution over several years.
The company itself expects the category to take 2-3 years to scale, making this more of a medium-term growth contributor than an immediate FY27 revenue driver.
Therefore, the counter-drone business should be viewed as a diversification option within EW, not as a substitute for Talon Shield in the near term.
EW Could Become Meaningful Without Taking Over The Entire Company
There is another important point in the numbers.
Data Patterns is targeting 20-25% revenue growth and around 35-40% EBITDA margins, while trying to build an order book equivalent to roughly three years of revenue. The company has also indicated that FY27 fresh order inflows could be around ₹2,000 crore, although management has acknowledged that some orders could slip into FY28 or later.
That means EW does not have to replace the existing business.
Suppose Data Patterns grows its existing business while EW adds ₹250 crore of annual revenue.
At the FY26 base, that would take revenue from ₹925 crore to ₹1,175 crore before considering any other growth.
At ₹500 crore of incremental EW revenue, the same base would become ₹1,425 crore.
In other words, EW can become a major growth engine alongside radars, avionics, BrahMos-related systems, space and other defence electronics.
That is a more realistic thesis than assuming the entire future of Data Patterns depends on one jammer.
The Biggest Upside Is The Combination Of Multiple EW Products
The strongest version of the EW thesis is therefore not:
“Data Patterns wins the ₹7,400 crore jammer market.”
It is:
“Data Patterns qualifies one major EW product, uses that credibility to win production, and then expands across adjacent EW programmes.”
The company already has RWR, ESM, COMINT/ELINT and jammer capabilities. Its counter-drone systems add another potential application. It is also developing threat emulators, radar target simulators and target data receivers.
This creates the possibility of an EW portfolio rather than a single-product business.
If one product reaches production, the engineering and IP developed around it can potentially support other applications.
That is where Data Patterns' reusable engineering architecture becomes important. The company has more than 1,500 reusable engineering building blocks, allowing it to reuse technology across different systems rather than developing every product completely from scratch.
If that model works in EW, the incremental economics could become more attractive as the portfolio expands.
But Qualification Is Still The Biggest Binary Risk
The biggest risk has not changed: technology success does not automatically become revenue.
Data Patterns has already experienced situations where technically capable products competed against imported alternatives or faced delays in platform selection. The company's internally funded development programmes can also remain in qualification for long periods before commercial production begins.
Talon Shield therefore needs to clear several gates:
Flight trials → qualification → customer/platform selection → production order → serial production → repeat orders.
A successful flight trial is only one step.
Even after qualification, the timing of procurement can determine when revenue actually appears. Large defence programmes can take considerably longer to convert than the original development timeline suggests.
That is why assigning a ₹370 crore, ₹740 crore or ₹1,480 crore revenue outcome to Talon Shield today would be premature.
What Investors Should Watch Over The Next 24-36 Months?
The EW thesis can be tracked with a fairly simple scorecard.
- Talon Shield flight trials: The immediate technical milestone.
- Qualification: This determines whether the product moves from development into the procurement pool.
- Production order: The first real financial validation. Investors should focus on order value and the number of aircraft/pods covered rather than market-size estimates.
- Annual production run-rate: This is what determines whether EW reaches the ₹250–500 crore threshold required to become a genuine growth engine.
- Counter-drone conversion: The initial one or two orders need to turn into larger multi-vendor procurement.
- Revenue disclosure: Eventually, investors need enough disclosure to determine how much of Data Patterns' revenue actually comes from EW.
This last point is particularly important. Today, EW is strategically significant, but its standalone financial contribution is not separately disclosed.
So, Can Electronic Warfare Become Data Patterns' Next Big Growth Engine?
Yes, but the evidence required to prove it is very specific.
The opportunity is large enough to matter. A ₹250 crore annual EW business would already equal more than a quarter of Data Patterns' FY26 revenue. A ₹500 crore business would represent more than half of the FY26 revenue base. The broader EW market and the ₹7,400 crore jammer opportunity are therefore large enough that even a relatively small share could materially change the company's scale.
But the company does not need to capture a theoretical 10% or 20% of the entire market for the thesis to work.
The real question is whether Talon Shield can move from flight trials into production, whether counter-drone systems can scale beyond trials, and whether Data Patterns can use its existing EW technology to win multiple programmes.
The most important number to watch is therefore not the ₹10,000 crore market size.
It is whether Data Patterns can build ₹250-500 crore of recurring annual EW revenue over time.
If it can, EW deserves to be called a genuine second growth engine.
If Talon Shield remains stuck in qualification, counter-drone orders remain small, and EW revenue stays embedded and immaterial within the broader business, then it remains what it is today: a high-upside opportunity, but not yet a proven growth engine.