Can Pearl Global Cross ₹6,000 Crore Revenue Ahead of Schedule?
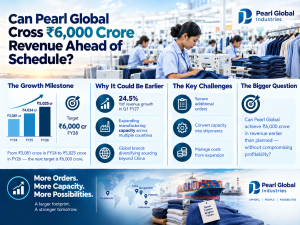
Pearl Global Industries is approaching a revenue milestone that could arrive earlier than originally planned. The apparel manufacturer reported ₹5,025 crore in consolidated revenue in FY26 and has set ₹6,000 crore as its next major target. Following a strong first quarter in FY27, management indicated that the company could reach this milestone before FY28.
The opportunity is supported by expanding manufacturing capacity, growing customer relationships and global apparel brands diversifying their sourcing locations. However, achieving ₹6,000 crore is only one part of the investment case. The more important questions are how much growth the company needs, whether its additional capacity can support that growth, and how much profit and cash the expansion will generate.
Five calculations help assess the opportunity: FY27 revenue scenarios, capacity-based revenue potential, EBITDA sensitivity, returns on planned capital expenditure and the working-capital burden of faster growth.
How Much Revenue Growth Is Required to Cross ₹6,000 Crore?
Pearl Global's FY26 consolidated revenue was ₹5,025 crore. Reaching ₹6,000 crore requires an additional ₹975 crore, equivalent to 19.4% growth.
Q1 FY27 provides an encouraging starting point. Revenue increased 24.5% year-on-year to ₹1,528 crore. Adjusted EBITDA, excluding ESOP expenses, rose 44.1% to ₹164 crore, while profit after tax increased 51.4% to ₹99 crore.
However, the full-year outcome depends on whether this momentum continues. The following scenarios illustrate what different FY27 growth rates would mean.
| FY27 revenue growth | Illustrative FY27 revenue | ₹6,000 crore achieved? |
| 15% | ₹5,778.75 Cr | No |
| 20% | ₹6,030 Cr | Yes |
| 25% | ₹6,281.25 Cr | Yes |
Source: Analyst calculations using FY26 revenue of ₹5,025 crore. These are scenarios, not company guidance.
The calculations show that 20% full-year growth would be sufficient to cross the target, while 15% growth would leave revenue ₹221.25 crore short.
There is another useful way to examine the requirement. After Q1 revenue of ₹1,528 crore, Pearl Global needs ₹4,472 crore over the remaining three quarters to reach ₹6,000 crore. That implies average quarterly revenue of approximately ₹1,490.7 crore for Q2-Q4.
This average is slightly below Q1 revenue, but it should not be interpreted as proof that the target is assured. Apparel shipments can be seasonal, customer orders can shift between quarters, and changes in tariffs or retail demand can affect sourcing decisions. Q1's 24.5% year-on-year growth may not continue at the same rate throughout FY27.
The key test is whether revenue remains close to the pace required for approximately 20% full-year growth.
Can Capacity Expansion Support Revenue Beyond ₹6,000 Crore?
Pearl Global's expansion plans provide a potential foundation for higher revenue. Management indicated that group installed capacity would reach approximately 108 million pieces by September-October 2026, with capacity expected to increase to 125-130 million pieces by FY28.
The relationship between shipments and revenue helps illustrate the opportunity.
In FY26, the company shipped 78 million pieces and generated ₹5,025 crore in revenue. This implies average revenue of approximately ₹644.23 per shipped piece.
Using that historical average, the revenue potential at higher shipment volumes can be calculated. The following estimates assume unchanged realisation per piece and are illustrative rather than forecasts.
| Annual shipments | Illustrative revenue |
| 78 million pieces | ₹5,025 Cr |
| 84 million pieces | ₹5,393.5 Cr |
| 90 million pieces | ₹5,779 Cr |
| 93.1 million pieces | ₹6,000 Cr |
| 100 million pieces | ₹6,442.3 Cr |
Source: Analyst calculations using FY26 revenue and shipments. Actual realisations, product mix and shipment volumes may differ.
The calculation indicates that Pearl Global would need approximately 93.1 million annual shipments to generate ₹6,000 crore at the FY26 average realisation. That is around 15.1 million more pieces than it shipped in FY26.
However, installed capacity and shipments are different measures. A capacity figure of 108 million pieces does not mean the company will automatically ship 108 million pieces in a year. Production efficiency, customer orders, factory ramp-up and the timing of new facilities will determine actual output.
At the FY26 shipment-to-capacity relationship, higher installed capacity could provide substantial room for growth. But the most important operational indicator will be whether shipments rise alongside capacity.
Pearl Global also needs to consider product mix. Higher-value garments can generate more revenue per piece, while changes in customer programmes and product complexity can alter the relationship between shipment volume and sales.
The capacity expansion therefore makes the ₹6,000 crore target more achievable, but the conversion of installed capacity into actual shipments will determine the outcome.
What Happens to EBITDA if Margins Fall Short?
Revenue growth creates value only when it translates into operating earnings. Pearl Global's Q1 FY27 adjusted EBITDA margin of 10.7% was encouraging, and management has expressed confidence in sustaining a double-digit EBITDA margin for FY27. Its FY28 margin aspiration is in the 10-12% range.
But higher wages, new-facility start-up costs and competitive pricing could prevent margins from reaching the upper end of that range.
The financial impact can be quantified at ₹6,000 crore revenue.
| EBITDA margin | EBITDA at ₹6,000 Cr revenue |
| 9% | ₹540 Cr |
| 10% | ₹600 Cr |
| 11% | ₹660 Cr |
| 12% | ₹720 Cr |
Source: Analyst calculations. These are illustrative outcomes, not management forecasts.
The difference between a 9% and 12% EBITDA margin is ₹180 crore annually. That is a substantial difference for a manufacturer pursuing rapid expansion.
Three factors will influence where Pearl Global lands within this range.
- Wage inflation: Higher labour costs can reduce the profit earned on each garment unless offset by productivity improvements, pricing or a better product mix.
- New-facility costs: Production facilities need time to reach efficient utilisation. Costs incurred during the ramp-up period can weigh on margins before the additional revenue fully materialises.
- Operating leverage: Higher factory utilisation can spread fixed costs over more shipments, improving profitability if incremental orders generate adequate contribution margins.
The first-quarter performance demonstrates that revenue and adjusted EBITDA can grow strongly together. It does not guarantee that the same margin will persist as the company adds capacity across different geographies.
The investor focus should therefore be on whether higher shipments improve factory utilisation sufficiently to offset wage inflation and expansion-related costs. A ₹6,000 crore business earning a 12% EBITDA margin would generate ₹180 crore more EBITDA than the same-sized business earning 9%. Check our latest video for more details.
Can ₹200-250 Crore of Capex Generate Adequate Returns?
Pearl Global has indicated planned FY27 capital expenditure of approximately ₹200-250 crore across geographies. The programme includes capacity additions and manufacturing infrastructure, with management also discussing development in India and Vietnam and further capacity in Bangladesh.
The investment should be assessed by the incremental earnings it generates rather than the amount of capacity it creates.
A simple way to establish a hurdle is to compare incremental annual EBITDA with the planned capex.
| Illustrative EBITDA-to-capex hurdle | On ₹200 Cr capex | On ₹250 Cr capex |
| 10% | ₹20 Cr | ₹25 Cr |
| 12% | ₹24 Cr | ₹30 Cr |
| 15% | ₹30 Cr | ₹37.5 Cr |
Source: Analyst calculations. The percentages are illustrative screening hurdles, not company targets or actual returns on invested capital.
For example, if ₹250 crore of investment eventually generates ₹30 crore of incremental annual EBITDA, the incremental EBITDA-to-capex ratio would be 12%. This does not mean the investment earns a 12% return on capital employed. EBITDA excludes depreciation, interest and taxes, while a complete return calculation must also account for working capital, existing assets, ramp-up time and the capital actually deployed.
The revenue needed to support these earnings depends on the incremental EBITDA margin. At an illustrative 10% incremental EBITDA margin, generating ₹20-30 crore of annual EBITDA would require ₹200-300 crore of additional annual revenue once the investment has ramped up.
The actual outcome will depend on which facilities receive the investment and how quickly their output is sold. The full ₹200-250 crore should not be assumed to produce incremental earnings immediately in FY27.
Guatemala could provide an additional earnings benefit
Management has expressed confidence that Guatemala will achieve break-even during FY27 after the company revised its operating strategy.
The significance is that break-even could reduce the drag from an underperforming operation and improve consolidated profitability relative to a situation in which Guatemala continues to incur operating losses.
However, break-even is not the same as generating a substantial profit. Management has not provided a quantified estimate of the EBITDA improvement that Guatemala's turnaround would deliver.
Consequently, the financial benefit should be monitored through actual operating performance rather than included as a fixed contribution to the capex return calculation.
The broader test is whether new investments and the Guatemala turnaround generate enough incremental EBITDA to justify the capital committed, without creating excessive funding requirements.
Will Faster Revenue Growth Consume More Cash?
A growing apparel business generally needs to fund production before it receives payment from customers. Additional revenue can therefore increase the amount tied up in inventory, work in progress and receivables.
This matters because reaching ₹6,000 crore ahead of schedule would be less attractive if the company had to commit substantially more cash to support every additional rupee of sales.
A reliable, current cash-conversion-cycle figure has not been established from the information used for this article. Rather than present an unverified working-capital ratio as a reported company figure, an illustrative funding sensitivity can show the potential scale of the requirement.
Pearl Global needs an additional ₹975 crore of annual revenue to move from ₹5,025 crore to ₹6,000 crore.
| Assumed incremental working capital as a share of additional revenue | Additional funding required |
| 10% | ₹97.5 Cr |
| 15% | ₹146.25 Cr |
| 20% | ₹195 Cr |
Source: Analyst calculations. These percentages are assumptions, not Pearl Global's reported working-capital ratios. The actual requirement depends on payment terms, inventory levels, supplier credit and customer collections.
Under these assumptions, the incremental working-capital requirement could range from ₹97.5 crore to ₹195 crore as revenue increases by ₹975 crore. These amounts are illustrative estimates of funding tied to incremental sales, not a forecast of the company's actual cash outflow.
The comparison with planned FY27 capex is revealing. At the 15% assumption, the additional working-capital requirement would be ₹146.25 crore, equivalent to more than half of the lower end of the planned capex range.
That means the funding requirement for growth may extend beyond factories and machinery. The business also needs to finance the production cycle associated with additional orders.
Investors should watch for changes in receivable days, inventory days, payable days and operating cash flow. If sales grow faster than collections, reported profit may increase while cash generation remains weak.
A faster revenue milestone becomes more valuable when it is accompanied by disciplined inventory management and timely customer collections.
Conclusion
Pearl Global needs approximately 19.4% growth over FY26 revenue to cross ₹6,000 crore. Its Q1 FY27 revenue growth of 24.5%, capacity expansion towards 108 million pieces and longer-term plan for 125-130 million pieces provide a foundation for reaching the milestone ahead of FY28.
The scenarios also show what could prevent the target from being achieved. Growth of 15% would leave FY27 revenue below ₹6,000 crore, while 20% growth would take it just above the milestone. Actual performance will depend on customer demand, shipments and the pace at which new facilities ramp up.
The earnings implications are equally important. At ₹6,000 crore revenue, EBITDA would range from ₹540 crore at a 9% margin to ₹720 crore at 12%. Meanwhile, planned capex and additional working-capital needs mean that faster growth must be evaluated alongside capital efficiency and cash generation.
The strongest investment signal would be Pearl Global reaching ₹6,000 crore while maintaining double-digit EBITDA margins, improving capacity utilisation and converting earnings into cash. That would demonstrate not only that the company can grow faster, but that its international manufacturing network can support a larger and more profitable business.