How Data Patterns Turns Defence Orders Into Profits?
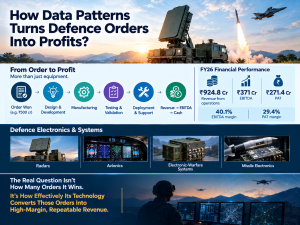
A defence order is only valuable when Data Patterns can convert it into revenue, protect its margin and eventually collect the cash. That distinction matters because the company’s FY26 numbers show how powerful the model can be: revenue from operations reached ₹924.77 Cr, EBITDA was ₹371.0 Cr, and PAT was ₹271.37 Cr. EBITDA margin was 40.1%.
But the investor question is not simply how many orders Data Patterns wins. It is what type of order it wins, where that order sits in the development-to-production cycle, how much margin it carries and how long the cash remains locked up.
That creates a better way to understand the company: development creates the product, production creates scale, IP protects the margin and collections determine how much of that accounting profit becomes cash.
Development Is The Investment; Production Is Where The Economics Scale
Data Patterns does not treat every defence order as the same type of revenue. Development contracts require the company to design and qualify a product, while production contracts come after that technology has been accepted and can be manufactured repeatedly.
The shift is visible in the company’s revenue mix. In FY23, development accounted for 66% of revenue and production 29%. By FY26, production had risen to 51% while development had fallen to 40%, with services making up the balance. In 9M FY26, production contributed 57% of revenue and development 37%.
This is the strongest evidence of the development-to-production flywheel but it is important not to overstate it.
Data Patterns does not disclose a cohort-level conversion rate showing that, for example, ₹100 Cr of FY23 development revenue directly became ₹X Cr of production revenue after a specified number of years. Management has instead said that the large development contracts taken over the previous two years have the potential to generate production orders multiple times their original value.
So the correct investor metric is not a manufactured conversion percentage. It is the rising share of production revenue and whether today's development products begin generating repeat production orders.
The ₹180 Crore Radar Order Shows Why Order Value Alone Can Mislead
The clearest example came in Q2 FY26, when Data Patterns delivered a strategic contract worth around ₹180 Cr. Management explicitly said it had accepted the contract at a competitive price because of potential long-term opportunities. The economics were immediately visible.
Q2 FY26 revenue from operations was ₹307.46 Cr, meaning this single contract represented nearly 59% of quarterly operating revenue. Gross margin fell to 38.52% from 75.96% in Q2 FY25, and the company directly attributed the decline to delivery of this strategic low-margin contract. EBITDA margin was 22.27%, versus 37.68% a year earlier.
This is an important distinction for investors: Data Patterns is willing to sacrifice near-term margin when an order can establish a position in a strategically important programme.
However, the company has not disclosed the exact gross or EBITDA margin of the ₹180 Cr contract. Therefore, calculating that contract's individual margin or its precise FY27/FY28 EBITDA dilution would require an assumption that the company has not provided.
What can be said with certainty is more useful: the contract demonstrated that revenue growth and margin expansion do not always move together. Product mix matters. Check our latest video for more details.
The ₹585.76 Crore BEL Order: The Earnings Potential Is Real, But The Timing Is Not Disclosed
In August 2026, Data Patterns received a ₹585.76 Cr order from Bharat Electronics for radar electronics. The order is important because it converted part of the previously negotiated opportunity into a firm contract. The company's filing states that the execution period is “as per contract”; it does not disclose a specific number of months or years.
That means the article should not pretend that the entire ₹585.76 Cr becomes FY27 revenue.
The correct way to frame the economics is through a sensitivity:
- At a two-year execution pace: ₹292.88 Cr of annual revenue.
- At a 35% EBITDA margin: ₹102.51 Cr of annual EBITDA.
- At the FY26 EBITDA margin of 40.1%: ₹117.44 Cr of annual EBITDA.
These are illustrative calculations, not management guidance or forecasts. The actual outcome depends on the contractual delivery schedule and the margin of this particular radar programme.
Cash has another layer. CRISIL says Data Patterns had 287 days of receivables at March 31, 2026, while its gross current assets were 424 days. Collections are linked partly to field and site acceptance testing, with some receivables also representing retention money.
So the ₹585.76 Cr order demonstrates the company's earnings potential, but its real financial contribution will only become visible as delivery, revenue recognition and collection happen in sequence.
The ₹727.77 Crore Figure Needs Correcting The Real Receivables Issue Is ₹328.85 Crore
The earlier analysis treated ₹727.77 Cr as government receivables. The audited FY26 balance sheet shows that this is incorrect.
As of March 31, 2026, Data Patterns reported:
- Trade receivables: ₹328.85 Cr
- Cash and cash equivalents: ₹727.77 Cr
- Bank balances other than cash and cash equivalents: ₹56.85 Cr
The ₹328.85 Cr trade-receivables balance was equal to 35.6% of FY26 revenue of ₹924.77 Cr. More important than the absolute number, however, is the ageing profile. CRISIL reported 287 receivable days, largely because collections are linked to customer acceptance and retention mechanisms.
This is where the 365-day cash-conversion cycle matters. A business can report a ₹100 Cr order, manufacture the equipment, recognise revenue and record EBITDA while still waiting months for the cash.
That creates a critical scaling question. As production orders become larger, Data Patterns must finance more inventory, work-in-progress and receivables before customers pay.
The balance sheet currently gives it room: the company remained net debt-free, with substantial cash and investments.
But that does not eliminate the risk. It simply means the company currently has a stronger buffer against its structurally long cash cycle.
The ₹131.19 Crore Product-Development Spend Is The Bridge To The Next Profit Pool
The most interesting part of Data Patterns' future is not the list of products. It is the amount already invested in getting those products ready.
The FY26 audited filing shows that of ₹167.24 Cr allocated from the QIP for product development, ₹131.19 Cr had been utilised by March 31, 2026, leaving ₹36.05 Cr unutilised.
The company's research materials identify products supported by this development programme, including Su-30 jammer pods, Hawk/fire-control radars, BrahMos seekers and satellite-related products. But these should not all be treated as production businesses today.
The pipeline has different stages:
- BrahMos seeker: development work had progressed to completed seeker trials, with management saying production orders would follow from the development contract.
- Jammer pod: moving through flight-trial/qualification stages; qualification is the key gate before production.
- Fire-control radar: development exists, but competitive and customer-qualification processes still matter.
- Satellite and newer systems: longer-term opportunities rather than current production revenue.
This distinction is crucial. ₹131.19 Cr is not an asset that automatically becomes revenue. It is capital deployed to create products that still have to cross qualification, acceptance and production gates.
The payoff can be substantial if those gates are cleared because Data Patterns can then reuse the underlying technology and building blocks across multiple systems.
The Real Profit Engine Is Not “Orders”; It Is The Order-Quality Ladder
Putting the numbers together creates a much clearer business model.
Development order → engineering and qualification → production order → repeat production → services/AMC
Each step changes the economics.
Development requires engineering expenditure and customer acceptance. Production creates larger manufacturing revenue. In-house IP can then support stronger gross margins because Data Patterns controls more of the technology rather than simply integrating bought-out components. Management has explicitly said that contracts with a higher proportion of in-house-designed products tend to produce higher gross margins.
FY26 demonstrates what the mature part of this model can look like: ₹924.77 Cr revenue, ₹371 Cr EBITDA and ₹271.37 Cr PAT, with a 40.1% EBITDA margin.
But the ₹180 Cr strategic order proves the reverse is also possible: a large contract can temporarily reduce profitability when Data Patterns prioritises strategic positioning.
That is why the headline order book should not be the only number investors track.
The better questions are:
- How much of the order book is production versus development?
- How quickly are development products reaching qualification?
- Are new production orders carrying the historical margin profile?
- Are receivable days falling as production becomes a larger share of revenue?
- Is operating cash flow keeping pace with EBITDA?
The Investor's Real Scorecard
Data Patterns has already shown that defence orders can generate unusually high operating margins. FY26 EBITDA margin was 40.1%, while Q4 FY26 reached 55.9%, demonstrating the benefit of favourable execution mix.
But the next phase requires a different kind of execution.
The company has to convert its development investments into production programmes without allowing qualification delays to stretch the cash cycle or strategic contracts to permanently dilute margins.
The most important indicators are therefore not simply new order announcements.
Watch four things:
- Production mix: FY26 was already 51% production, compared with 29% in FY23.
- Development conversion: whether products funded through the ₹131.19 Cr development investment begin generating repeat production orders.
- Margin quality: whether the company can sustain its 35-40% guidance band despite strategic low-margin contracts.
- Cash conversion: whether the 287-day receivable cycle and 424-day gross-current-asset cycle continue improving as production scales.
The central insight is simple: Data Patterns does not make its best money when it wins a defence order. It makes its best money when a product it has already developed becomes a qualified, repeatable production programme and the resulting EBITDA eventually turns into cash.
That is the difference between having a large defence order book and building a compounding defence-electronics business.