Why PTC Industries’ Biggest Opportunity May Also Be Its Biggest Risk?
PTC Industries is building the kind of manufacturing capability that can fundamentally change the size of its business. Its new aerospace and advanced-materials platform combines specialised melting, refining, forging and rolling capabilities that could allow the company to participate in much more of the aerospace and defence value chain.
But the same expansion creates PTC's biggest financial risk.
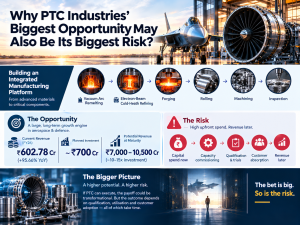
The company is investing roughly ₹700 crore in this platform against a FY26 consolidated revenue base of ₹602.78 crore. Management has indicated that the investment could eventually support revenue of 10-15 times the capital invested.
That would imply a potential revenue opportunity of ₹7,000-10,500 crore.
The important word is potential.
The 10-15× number should not be read as a near-term revenue forecast or as a guaranteed return on the ₹700 crore. It represents management's view of the mature revenue potential of the investment, while the exact maturity timeline has not been disclosed.
That creates the central investment question: can PTC convert the new capacity into high utilisation, serial production, strong margins and cash returns quickly enough to justify the capital being deployed today?
What Does The 10-15× Claim Actually Mean?
The ₹7,000-10,500 crore figure comes directly from applying management's 10-15× revenue-potential statement to the roughly ₹700 crore investment.
It is therefore important to separate three things.
First, this is not FY28 revenue guidance.
Second, it is not the revenue currently generated by the new facilities.
Third, it is not a disclosed ROCE or profit target.
The investment covers PTC's expanding advanced-materials and component-manufacturing platform, including the SMTC infrastructure at Lucknow. The facility includes a 1,500-tonne-per-annum VAR furnace, around 5,000 tonnes of EBCHR capacity, and roughly 4,500-5,100 tonnes of forging capacity, alongside rolling capabilities.
Management's 10-15× statement refers to the revenue potential once the investment reaches maturity. However, PTC has not disclosed a precise year in which that mature state is expected to be achieved.
That makes the ₹7,000-10,500 crore figure useful as a long-term scale indicator, but not as an earnings forecast.
The more relevant question for investors is how quickly PTC moves from today's ₹602.78 crore business to commercial production from the new platform and then toward mature utilisation.
The Starting Point Is Still Only ₹602.78 Crore Of Revenue
The scale of the opportunity becomes clearer when the starting point is kept separate from the future potential.
PTC reported ₹602.78 crore of consolidated revenue in FY26, with EBITDA of ₹172.28 crore and PAT of ₹101.56 crore.
Aerolloy contributed more than ₹175 crore in FY26, while Trac contributed ₹247.01 crore.
These are important because they demonstrate that PTC already has operating businesses connected to aerospace, precision engineering and advanced manufacturing.
But they should not be counted as revenue from the new ₹700 crore project.
The new platform is an expansion of manufacturing capability rather than a replacement for the existing business.
The progression investors need to track is therefore:
FY26: ₹602.78 crore consolidated revenue and ₹317.32 crore of capex.
FY27: commissioning, trials, qualification and continued ramp-up of the existing businesses.
FY28: commercialisation of the SMTC platform, with operations expected from Q1 FY28.
Beyond FY28: increasing customer conversion, serial production and utilisation.
Maturity: management's stated potential of 10-15× the investment, or ₹7,000-10,500 crore based on ₹700 crore of investment.
The distance between the first and last numbers is the opportunity.
It is also the execution risk.
What Could ₹700 Crore Actually Earn?
PTC has not disclosed project-level EBITDA, ROCE or payback targets. That means investors have to separate management's revenue opportunity from their own return assumptions.
The following is analyst sensitivity, not management guidance.
| Mature revenue | 20% EBITDA margin | 25% EBITDA margin | 30% EBITDA margin |
| ₹7,000 Cr | ₹1,400 Cr | ₹1,750 Cr | ₹2,100 Cr |
| ₹8,750 Cr | ₹1,750 Cr | ₹2,188 Cr | ₹2,625 Cr |
| ₹10,500 Cr | ₹2,100 Cr | ₹2,625 Cr | ₹3,150 Cr |
Against ₹700 crore of investment, even the lower-end revenue case produces substantial operating leverage if the assumed margins are achieved.
At ₹7,000 crore revenue and a 20% EBITDA margin, the platform would generate ₹1,400 crore of EBITDA. At the midpoint revenue of ₹8,750 crore and a 25% margin, EBITDA would be approximately ₹2,188 crore.
But these numbers should not be called project ROCE.
True ROCE requires operating profit after depreciation and tax relative to the capital employed, and PTC has not disclosed the project-level depreciation profile, working-capital requirement, tax allocation or capital employed at maturity.
A more honest way to view the sensitivity is as an EBITDA yield on the ₹700 crore investment.
Under the above assumptions, the EBITDA generated would be equivalent to roughly 2.0× to 4.5× the initial investment annually once fully mature.
That shows why the opportunity is so large but it also shows how much depends on the assumptions.
Utilisation Is The Real Stress Test
The biggest risk can be quantified without pretending that PTC has already disclosed a utilisation target.
Take the midpoint of management's potential revenue range: ₹8,750 crore at full maturity.
If that revenue potential scales broadly with utilisation, the implied revenue sensitivity would look like this:
| Utilisation | Implied revenue | EBITDA at 20% | EBITDA at 25% | EBITDA at 30% |
| 30% | ₹2,625 Cr | ₹525 Cr | ₹656 Cr | ₹788 Cr |
| 50% | ₹4,375 Cr | ₹875 Cr | ₹1,094 Cr | ₹1,313 Cr |
| 70% | ₹6,125 Cr | ₹1,225 Cr | ₹1,531 Cr | ₹1,838 Cr |
Again, these are analyst scenarios, not PTC's guidance.
The table demonstrates why utilisation matters more than headline installed capacity.
At 30% utilisation, even the midpoint mature opportunity would produce only ₹2,625 crore of revenue under this simplified framework. At 70%, it would be ₹6,125 crore.
The same installed assets can therefore generate radically different economic outcomes depending on how quickly customer programmes ramp.
And there is an additional complication: revenue does not automatically equal cash generation.
PTC's FY26 operating cash flow was negative ₹68.66 crore, despite reporting ₹101.56 crore of PAT. Inventory was ₹299.01 crore, including ₹222.24 crore of work-in-progress, while receivables stood at ₹273.93 crore.
So the key milestone is not simply reaching 30%, 50% or 70% utilisation.
It is reaching those levels without allowing working capital to consume the EBITDA being generated.
The Cash-Flow Risk Is Already Visible
PTC's expansion is taking place during a period of heavy capital expenditure.
FY26 capex was ₹317.32 crore. Capital work in progress stood at ₹310.65 crore, while property, plant and equipment was ₹737.34 crore.
At the same time, operating cash flow was negative.
That combination matters because the new business requires capital before it produces its full economic contribution.
The company is effectively carrying three different financial burdens during the transition:
- Capex: money spent to build and commission new capacity.
- Working capital: inventory and receivables required to support production and customer programmes.
- Qualification costs and time: products must move through testing and customer approval before serial production.
This means EBITDA from the mature scenario cannot simply be treated as free cash flow.
Interest, taxes, working-capital investment, maintenance capex and the timing of customer payments all sit between EBITDA and actual cash generation.
That is why the most important financial milestone after commercialisation will be positive and sustainably rising operating cash flow, not just revenue growth. Check our latest video for more details.
The Qualification Risk Should Be Viewed As One Conversion Chain
PTC's aerospace opportunity spans customers and programmes involving Airbus, Safran, Honeywell and Blue Origin, alongside defence and space opportunities including BrahMos and programmes involving organisations such as DRDO, GTRE and ISRO.
That gives the company access to attractive markets.
But the investor should track the opportunity through a simple conversion chain:
Customer engagement → qualification → approval → serial production → volume ramp → capacity utilisation → cash generation.
Failure at any point can delay the economics of the ₹700 crore investment.
For example, winning a programme does not immediately fill a forging line. A qualified component does not immediately reach mature production volumes. And production revenue does not necessarily translate into cash if inventory and receivable days remain elevated.
This is why PTC's future disclosures around qualification completion, customer approvals, production volumes and utilisation will be more informative than simply announcing additional programmes.
The opportunity becomes financially meaningful only when those programmes start consuming capacity.
Aerolloy And Trac Provide The Bridge But Not The Answer
PTC enters this expansion with a stronger base than a company building an aerospace business from scratch.
Aerolloy generated more than ₹175 crore in FY26 and ₹74.3 crore in Q1 FY27. Its Q1 FY27 EBITDA was ₹33.4 crore.
Trac generated ₹247.01 crore in FY26 and ₹71.4 crore in Q1 FY27.
These businesses provide existing customers, manufacturing expertise and a commercial base from which PTC can expand.
But their revenue should not be used to imply that the ₹700 crore project is already generating its eventual returns.
The distinction is especially important for Aerolloy.
Aerolloy's existing revenue represents the performance of an operating subsidiary; it is not separately disclosed as revenue attributable to each new furnace or piece of SMTC infrastructure.
The correct investment bridge is therefore:
₹602.78 crore FY26 consolidated revenue → FY27 operating ramp and qualification → FY28 SMTC commercialisation → increasing serial-production volumes → mature utilisation → ₹7,000–10,500 crore potential revenue.
That is a much more demanding journey than simply adding the existing Aerolloy and Trac revenue to the future project opportunity.
What Investors Should Watch From FY28 Onward?
The next phase of PTC's story should be judged through operational milestones rather than headline announcements.
The first is commercial commissioning. The company has indicated that SMTC commercialisation is expected from Q1 FY28.
The second is qualification. The key question is how quickly the newly available materials and forged products receive customer approvals.
The third is production conversion. Investors need to see qualified products moving into recurring serial production rather than remaining in trial or development batches.
The fourth is utilisation. Installed tonnes are useful only when customers actually consume them.
The fifth is margin conversion. Revenue growth needs to translate into EBITDA rather than simply increasing fixed costs and working capital.
The sixth is cash conversion. Operating cash flow should eventually improve as production scales and the business absorbs its earlier investment.
These milestones create a much better scorecard than simply tracking the ₹7,000-10,500 crore headline opportunity.
The Downside Is Not That PTC Has Built The Wrong Factory
The more realistic downside scenario is that the factory takes longer to reach economic utilisation.
That would create a mismatch between when PTC spends the money and when customers generate enough production demand to absorb the capacity.
In that scenario, PTC could have:
high installed capacity + low utilisation + elevated WIP + high receivables + continuing depreciation and financing costs.
The result would be weaker returns on the capital already invested.
This is particularly important because PTC's new infrastructure is highly specialised. It is not generic manufacturing capacity that can necessarily be redirected to any customer if one programme is delayed.
The upside is equally clear.
If qualification converts into serial production, customer volumes scale and utilisation rises toward mature levels, the same fixed manufacturing platform can generate much higher revenue and EBITDA than the current business.
That is the operating leverage embedded in the strategy.
PTC is therefore not making a simple bet on aerospace demand.
It is making a bet that its customers will absorb a large amount of newly created specialised capacity at attractive economics.
The Opportunity And The Risk Are The Same Thing
The most interesting part of PTC's strategy is that its opportunity and risk cannot really be separated.
The company is building a vertically integrated platform that can potentially address a much larger portion of the aerospace and defence value chain.
Management's 10-15× revenue-potential statement illustrates the scale: approximately ₹7,000-10,500 crore of potential mature revenue against roughly ₹700 crore of investment.
But that number only becomes economically meaningful when the company demonstrates the path from capacity to utilisation.
The key unknowns are now clear.
- How quickly will the facilities qualify?
- How much production will customers actually place?
- How quickly will utilisation rise?
- What EBITDA margin will the mature business generate?
And most importantly, how much of that EBITDA will ultimately become operating cash flow?
Those questions determine whether the ₹700 crore investment becomes a transformational growth engine or a long-duration capital commitment with lower-than-expected returns.
Conclusion
PTC Industries is attempting to build a business several times larger than the one it has today.
The opportunity is substantial: management's stated 10-15× mature revenue potential implies ₹7,000-10,500 crore against roughly ₹700 crore of investment. Even conservative analyst scenarios show significant EBITDA potential if utilisation and margins reach attractive levels.
But none of that is guaranteed.
The ₹700 crore is being spent before the full revenue opportunity exists. Qualification takes time, specialised capacity needs customer absorption, and PTC's existing working-capital intensity means EBITDA cannot automatically be treated as cash.
That makes the next phase unusually important.
FY28 commercialisation is only the starting point. The real proof will come from qualification, serial production, utilisation, margins and operating cash flow.
PTC's biggest opportunity is therefore also its biggest risk: the company has built the capacity for a much larger business, but now it has to prove that customers will fill it.