Can Unimech’s Saudi JV Become a New Growth Driver?
Unimech Aerospace is putting US$30 million behind a Saudi manufacturing platform that is expected to generate US$80 million of cumulative revenue over five years. On paper, that is a 2.67x cumulative revenue-to-investment ratio. But the more revealing number is the endpoint: the JV is targeting US$30 million of annual revenue by Year 5, roughly equal to the entire project investment.
For context, Unimech generated ₹240.49 crore of revenue from operations in FY26, while the Saudi JV is targeting US$30 million of annual revenue in Year 5. Using the FY26 average USD/INR rate of ₹88.307, Unimech’s FY26 revenue was equivalent to US$27.23 million. On that basis, the Year-5 Saudi revenue target would be about 1.10 times Unimech’s FY26 revenue, while the five-year cumulative target would be about 2.94 times FY26 revenue.
That makes the opportunity material if delivered but not immediate. The first year is expected to generate only US$1 million, meaning the business must scale 30-fold by Year 5.
The real question is therefore how quickly the US$30 million investment turns into revenue, profit and utilisation.
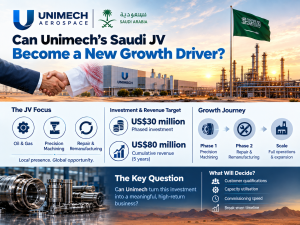
The US$30 Million Investment Needs To Be Viewed Against US$80 Million Of Revenue
The headline numbers become more useful when put together.
| Metric | Disclosed figure |
| Total phased investment | US$30 million |
| Five-year cumulative revenue | US$80 million |
| Revenue / investment | 2.67x |
| Year-1 revenue | US$1 million |
| Year-5 revenue | US$30 million |
| Year-5 EBITDA target | US$10.5 million* |
| Year-5 PAT target | US$6 million* |
*Calculated by applying the company’s disclosed 35% EBITDA and 20% PAT targets to the US$30 million Year-5 revenue target. These are target economics, not achieved results.
There is an important catch: US$80 million is cumulative revenue, not profit and not annual revenue. The company has disclosed only US$1 million for Year 1 and US$30 million for Year 5. Therefore, the remaining US$49 million of revenue has to come across Years 2-4, but the company has not disclosed how that US$49 million is distributed between those years.
If the 35% EBITDA and 20% PAT margins were hypothetically achieved across the entire US$80 million cumulative revenue, they would imply US$28 million of cumulative EBITDA and US$16 million of cumulative PAT. But that should not be treated as the company’s forecast because management has specified those margins only for the end of Year 5.
This is why the US$30 million investment should not be judged simply on a 2.67x revenue multiple. The critical question is how much of that revenue is generated after the facility reaches sufficient utilisation and margins.
23 CNC Machines Create A Clear Capacity Milestone But Utilisation Is Not Yet Quantifiable
The project plans to deploy 23 advanced CNC machines over three years, alongside API- and ISO-certified processes. This provides a concrete way to track the physical ramp-up.
But the current disclosure does not provide machine-wise capacity, available machining hours, expected revenue per machine or utilisation assumptions. Therefore, an exact percentage utilisation required to produce US$30 million of revenue cannot be calculated without introducing an unsupported assumption.
What can be calculated is the required revenue productivity:
US$30 million ÷ 23 CNC machines = US$1.304 million revenue per machine at the Year-5 target, assuming all 23 machines are deployed by then.
The three-year deployment schedule also means the business cannot be evaluated purely on Year-5 capacity. Investors should track the sequence:
- Year 1: US$1 million revenue target and initial commercialisation.
- Years 1-3: deployment of 23 CNC machines.
- Year 3: management’s targeted break-even point.
- Year 5: US$30 million revenue target and 35% EBITDA/20% PAT targets.
- Beyond machining: API-certified remanufacturing and repair.
This gives investors measurable checkpoints instead of relying on broad claims about execution.
A missed commissioning schedule would push revenue generation and break-even further out. Conversely, early customer qualification and higher revenue per machine could allow the facility to reach the targeted economics with the planned asset base.
YBAK’s Customer Access Is More Than A Strategic Claim
The strongest evidence supporting the local-partner rationale is not the JV announcement itself. It is YBA Kanoo’s existing industrial and energy footprint.
YBA Kanoo’s own corporate material says its Oil & Gas division has a GCC client base that includes Saudi Aramco, SABIC and Ma’aden, among others. It also describes relationships with the oil, gas and petrochemical industries and activities covering drilling, flow control, process solutions and other industrial services.
There is additional evidence from YBA Kanoo’s Saudi operations. Its Technical Contracting Company was described as an approved vendor to Saudi Aramco, SABIC, Saudi Electricity Company, SWCC, Ma’aden and the Royal Commission, with operations in mechanical, electrical, instrumentation, contracting and maintenance.
This gives the JV a tangible customer-access advantage: YBAK already operates inside industrial procurement ecosystems that overlap with the markets the JV is targeting.
But there is an important distinction.
Existing customer relationships do not equal orders for the new JV.
Neither Unimech’s January announcement nor its February investor presentation discloses a Saudi customer contract, purchase order or committed revenue from these named customers for the JV.
Therefore, the evidence supports YBAK’s access, but not yet the conversion of that access into US$80 million of contracted revenue.
The first customer qualification and first purchase order will be much more important evidence than the partnership announcement itself.
The Milestones Investors Should Track Are Now Very Specific
The Saudi strategy can be monitored through a sequence of commercial and financial milestones.
| Milestone | What it proves | Financial significance |
| Facility commissioning | Assets are operational | Starts revenue-generating phase |
| CNC deployment | Planned capacity is being installed | Determines available production capacity |
| First customer qualification | Market acceptance begins | Opens path to recurring orders |
| First purchase order | Strategy converts into commercial demand | Establishes actual revenue visibility |
| Year-3 break-even | Operating model covers costs | Validates ramp-up economics |
| 23-machine deployment | Planned asset base is substantially established | Tests capital productivity |
| US$30m Year-5 revenue | Scale target is reached | Equals 1x project investment annually |
| 35% EBITDA margin | Operating economics mature | US$10.5m implied EBITDA at target revenue |
| 20% PAT margin | Bottom-line economics mature | US$6m implied PAT at target revenue |
| API-certified remanufacturing | Higher-value capability added | Expands beyond machining |
This framework also exposes where the project could fall short.
If machines are commissioned but customer qualifications take longer, capacity could remain underutilised, if customer qualifications happen but purchase orders are small, revenue could lag the planned ramp and if revenue grows but margins remain below target, the US$30 million investment may generate less operating profit than expected.
The milestones therefore need to be read together rather than individually.
Remanufacturing Could Change The Economics Of The Platform
The longer-term opportunity is not limited to CNC machining.
Unimech and YBAK plan to develop the facility into an API-certified remanufacturing and repair platform serving upstream and downstream oil & gas customers. Utilities and mining are also identified as target markets.
That matters because machining and repair have different economic characteristics.
A machining business primarily monetises manufacturing capacity. Remanufacturing can potentially monetise the installed equipment base of customers through repair, refurbishment and lifecycle support.
YBAK already has relevant exposure to this type of industrial activity. Its Power & Industrial Projects division provides repair, refurbishment, reconditioning and maintenance-related services, while its Industrial & Energy operations serve utilities, refineries, petrochemical companies and other industrial customers.
However, the Saudi JV has not yet demonstrated revenue from this activity. API certification is therefore a future commercial milestone, not an existing earnings contributor.
For investors, the progression matters:
CNC machining → customer qualification → recurring orders → API certification → remanufacturing/repair
If the platform reaches the later stages, its addressable revenue model becomes broader than simply selling machining hours.
What Would Make The Saudi JV Meaningful For Unimech?
The US$80 million cumulative revenue target is meaningful relative to Unimech’s current scale, but its timing matters.
Unimech reported FY26 revenue from operations of ₹240.49 crore, EBITDA of ₹75.11 crore and PAT of ₹63.28 crore.
Using the FY26 average USD/INR rate of ₹88.307, that revenue from operations equates to US$27.23 million. On the same basis:
- US$30 million Year-5 revenue = 1.10x FY26 revenue
- US$80 million cumulative five-year revenue = 2.94x FY26 revenue
- US$10.5 million Year-5 EBITDA = 39.5% of FY26 EBITDA
- US$6 million Year-5 PAT = 20.7% of FY26 PAT
The last two comparisons are mechanical currency conversions and should not be read as forecasts of consolidated earnings contribution, because the JV is 51% owned and its accounting treatment, taxes, minority interest and eventual distributions will determine what reaches Unimech’s consolidated numbers.
Still, the scale comparison shows why the project matters. A US$30 million annual revenue operation would not be a marginal addition to a company whose FY26 revenue was equivalent to US$27.23 million.
The catch is that this scale is targeted for Year 5, not the immediate future. Check our latest video to know more.
Conclusion: The Numbers Make Saudi Material, But The Ramp-Up Is The Investment Test
Unimech’s Saudi JV is not a small geographical extension. It involves a US$30 million phased investment, 23 CNC machines, a 51% controlling stake and a target of US$80 million cumulative revenue over five years.
The arithmetic makes the opportunity significant: cumulative revenue is 2.67 times the planned investment, while the Year-5 revenue target equals the entire US$30 million project investment. At the disclosed Year-5 margins, that would imply US$10.5 million EBITDA and US$6 million PAT.
But the financial path is still largely undisclosed. Apart from US$1 million in Year 1 and US$30 million in Year 5, management has not provided annual revenue figures for Years 2-4 or year-wise EBITDA and PAT. The company also has not disclosed machine-level capacity or utilisation assumptions that would allow the US$30 million target to be independently converted into a utilisation percentage.
The evidence for YBAK’s customer access is stronger: its industrial and energy businesses have documented relationships with customers including Saudi Aramco, SABIC and Ma’aden. But no JV-specific orders from those customers have been disclosed.
That leaves a clear scorecard: commissioning, customer qualification, first PO, CNC utilisation, Year-3 break-even, US$30 million Year-5 revenue and API certification.
If those milestones arrive on schedule, the Saudi operation can become a second business of meaningful scale. Until then, the US$80 million remains a target whose value depends on how efficiently the US$30 million investment is converted into productive capacity and recurring customer revenue.